VA Loan Myths (And What Actually Matters)
If you’re using your VA loan benefit for the first time—or the fifth—there’s a lot of noise out there.
Friends mean well. Online forums are loud. And some real estate advice hasn’t been updated in years.
For PCS families relocating to San Antonio, misinformation can cost time, leverage, and confidence.
Let’s separate myth from reality so you can make strategic, informed decisions.
Bottom Line Up Front
- You do not need perfect credit to use a VA loan.
- There is no official VA loan limit if you have full entitlement.
- Sellers don’t automatically reject VA buyers when the offer is structured properly.
- The VA appraisal is not a deal killer—it’s a risk management tool.
- What matters most: preparation, lender quality, and strategy.
Why This Matters
The VA loan is one of the strongest mortgage products in the country.
Zero down. No private mortgage insurance (PMI). Competitive interest rates.
Yet many military families underuse it—or fear using it—because of outdated myths.
In a competitive San Antonio market near Joint Base San Antonio (JBSA), clarity creates leverage.
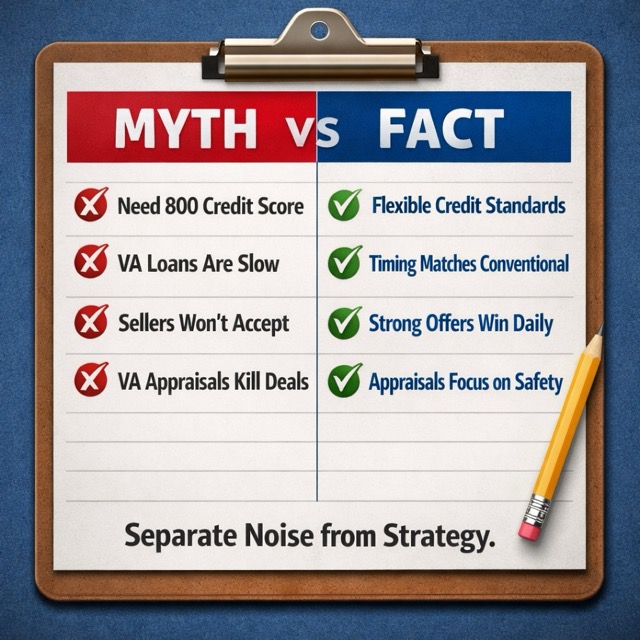
Myth #1: You Need Perfect Credit
Reality: The VA does not set a minimum credit score.
Lenders do. Most require scores in the 580–620 range, though stronger scores improve rate options.
What Actually Matters
- Stable income
- Manageable debt-to-income ratio (DTI)
- Clean payment history in the past 12 months
A 680 score with stable income often outperforms a 740 score with unstable employment.
Myth #2: VA Loans Take Too Long to Close
Reality: VA loans close at similar timelines as conventional loans when handled by experienced lenders.
Most San Antonio VA purchases close in 30–40 days.
What Slows Things Down
- Incomplete documentation
- Inexperienced VA lenders
- Appraisal access delays
Preparation—not the loan type—determines speed.
Myth #3: Sellers Hate VA Loans
Reality: Sellers care about certainty.
They fear appraisal gaps and repair requirements—not the VA itself.
How to Compete
- Use a lender known locally
- Provide strong pre-approval, not just pre-qualification
- Limit unnecessary contingencies
- Understand appraisal gap strategies
In areas near JBSA Randolph or Lackland, VA offers win daily when structured correctly.
Myth #4: VA Appraisals Are Too Strict
Reality: VA appraisals focus on safety, sanitation, and structural soundness.
They are not cosmetic inspections.
Common Triggers
- Peeling paint in older homes
- Roof damage
- Broken windows
- Non-working HVAC systems
Most issues are minor and repairable before closing.
Myth #5: There Are VA Loan Limits
Reality: If you have full entitlement, there is no loan limit.
You can purchase above conforming loan limits without a down payment—provided income supports it.
Limits apply only when entitlement is partially used.
Myth #6: You Can Only Use It Once
Reality: You can use your VA benefit multiple times.
You can even have more than one VA loan simultaneously under certain conditions.
Step-by-Step Game Plan for PCS Buyers
- Confirm eligibility and Certificate of Eligibility (COE).
- Get fully underwritten pre-approval.
- Review entitlement status.
- Analyze payment comfort zone—not max approval.
- Target neighborhoods aligned with commute to JBSA.
- Structure offer with appraisal awareness.
- Plan for funding fee impact.
Costs, Timing, and Variables
Funding Fee
A one-time fee ranging typically from 1.25%–3.3% depending on use and down payment.
Can be rolled into the loan.
Closing Costs
VA limits certain buyer-paid fees. Sellers can contribute up to 4% toward concessions.
Timeline
30–40 days typical in San Antonio markets.
Pitfalls and Solutions
- Pitfall: Shopping price instead of payment. Solution: Reverse engineer monthly comfort first.
- Pitfall: Using inexperienced lenders. Solution: Choose VA-volume lenders.
- Pitfall: Ignoring appraisal condition. Solution: Pre-evaluate older homes carefully.
FAQ
1. Do VA loans require mortgage insurance?
No. There is no PMI.
2. Can I buy a duplex?
Yes, up to four units if owner-occupied.
3. Is zero down required?
No. You may put money down if desired.
4. Can closing costs be covered?
Yes, through seller concessions or lender credits.
5. Are rates higher?
Often lower than conventional loans.
6. What if appraisal comes in low?
You can renegotiate, pay the difference, or walk away using the VA escape clause.
7. Can I use it after PCS?
Yes, if you intend to occupy the property.
8. Does the VA inspect the home?
No. Appraisal is not a full inspection.
San Antonio Context
San Antonio remains one of the most military-friendly housing markets in the country.
Areas near JBSA Lackland, Randolph, and Fort Sam Houston routinely see VA-backed offers.
Builders and resale sellers are familiar with VA standards.
Quick Checklist
- Confirm COE
- Review credit profile
- Calculate DTI
- Plan funding fee strategy
- Choose experienced VA lender
- Understand appraisal expectations
Next Best Step
Option 1: DIY
Download a VA loan readiness checklist and interview lenders.
Option 2: Professional Help
Work with a VA-experienced real estate and lending team familiar with JBSA timelines.
Option 3: Low-Pressure Consult
Schedule a strategy session to review entitlement, payment range, and San Antonio neighborhoods aligned with your PCS timeline.
The VA loan is not complicated. It is simply misunderstood.
When used strategically, it becomes one of the most powerful financial tools available to military families.